Author: Addithive

  • Casting vs Forging vs Additive Manufacturing: When Does AM Actually Remove the Bottleneck?

    Casting vs Forging vs Additive Manufacturing: When Does AM Actually Remove the Bottleneck?

    Additive manufacturing does not remove every aerospace bottleneck. Sometimes it removes tooling and long-lead forgings; sometimes it simply moves the constraint into powder, HIP, machining, CT/NDT or qualification. The right comparison is total program constraint, not printer cycle time.
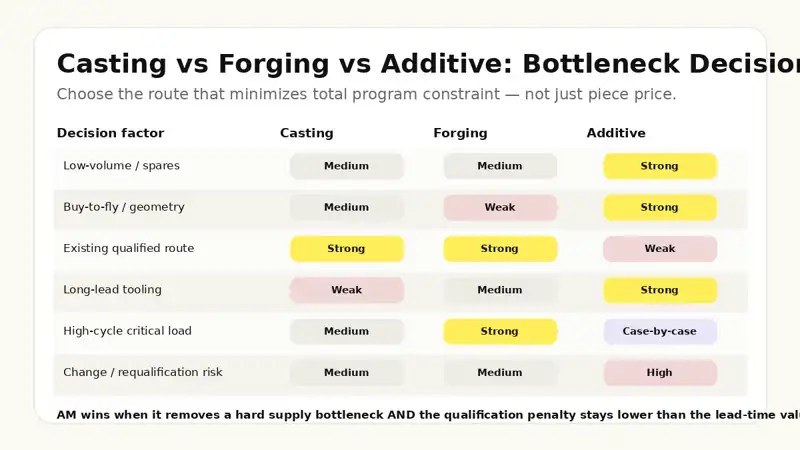
    Decision matrix comparing casting, forging and additive manufacturing across supply-chain and qualification factors.
    A practical decision map: AM is most valuable when it removes a hard supply bottleneck and the qualification penalty is smaller than the lead-time value created.

    Why this question matters in 2026

    Aerospace supply chains are still constrained by engines, electronics, castings, forgings, titanium and high-temperature alloys. Deloitte’s 2026 aerospace and defense outlook describes AM as a targeted resilience tool for low-volume, long-lead or hard-to-source parts—not as a universal replacement for conventional manufacturing.

    The constraint is visible in corporate actions, too. In September 2026, GE Aerospace announced an agreement to acquire Consolidated Precision Products, explicitly framing mission-critical casting capacity as necessary to support demand across commercial engines, aftermarket and defense. When an OEM is willing to spend billions to secure casting capacity, “just print it” is clearly not the default answer—but neither is “stay with the legacy route forever.”

    The bottleneck-removal test

    Before choosing AM, ask four questions in sequence:

    1. What is the actual constraint? Tooling? Raw material? Forge/foundry capacity? Buy-to-fly? Machining? Supplier minimum order quantity? Obsolescence?
    2. Can AM remove that constraint technically? Does the geometry, alloy, size and property requirement fit a mature process route?
    3. What new constraint does AM introduce? Powder/feedstock, build rate, support removal, HIP, heat treatment, machining, surface finish, CT/NDT, machine equivalence or qualification?
    4. Is the net program value positive? Compare avoided lead time and inventory against qualification, post-processing, yield and recurring cost.

    Casting vs forging vs additive: the decision matrix

    Part / program conditionCastingForgingAdditive
    High annual volume with stable geometryUsually strong once tooling/process are establishedStrong for load-critical shapes if capacity existsOften weak on unit economics unless geometry creates major value
    Low volume / spares / obsolescenceTooling and MOQ can hurtSmall lots can be difficultOften strong, especially with digital inventory
    Very high structural load / fatigue criticalityApplication-dependentOften preferred due to mature property pedigreePossible, but qualification and defect tolerance can dominate
    Complex internal flow pathsPossible but tooling/core complexity risesUsually poor fitStrong technical fit; inspectability may become the gate
    Extreme buy-to-fly ratioPotentially goodCan still require heavy machiningPotentially strong for expensive Ti/Ni alloys
    Long tooling lead timeWeak for urgent demandDies/tooling can constrain responseStrong if a qualified AM route already exists
    Existing mature qualified supply chainStrongStrongAM must overcome a qualification penalty to justify change
    Supplier capacity crisisMay be the bottleneckMay be the bottleneckCan be a resilience route if downstream AM capacity is actually available

    When AM genuinely removes the bottleneck

    1. Low-volume, long-lead hardware

    AM is strongest when tooling amortization is poor, demand is intermittent and carrying inventory is expensive. Legacy spares, defense sustainment hardware and space components often fit this pattern.

    2. Titanium or nickel parts with punitive buy-to-fly

    If the conventional route starts from a large billet or forging and machines most of it away, near-net AM can reduce raw-material exposure. That advantage is most valuable when alloy supply is constrained or scrap recovery does not fully compensate for long lead time.

    3. Tooling is the pacing item

    Investment-casting tooling, cores, forging dies and associated development loops can make the calendar inflexible. AM can collapse tooling time—but only if the AM process route is already mature enough to avoid replacing a tooling delay with a qualification delay.

    4. Part consolidation removes supplier interfaces

    A printed assembly that eliminates multiple details, welds, braze joints, fasteners or supplier handoffs may remove more schedule risk than its unit cost suggests. The value is system-level simplification.

    When AM only transfers the bottleneck

    • Powder/feedstock: a constrained or single-source alloy can recreate the same upstream dependency.
    • HIP and heat treatment: downstream special-process capacity may become the new queue.
    • Machining: AM rarely eliminates all machining for aerospace interfaces and critical surfaces.
    • CT/NDT: complex internal geometry can require expensive inspection with limited throughput.
    • Surface integrity: fatigue-critical parts may need substantial finishing and validation.
    • Qualification: the biggest trap is switching to AM to save six months of sourcing and then spending 18 months proving the new route.

    The qualification penalty

    The correct economic model should treat qualification like an up-front switching cost. A legacy casting or forging route may have terrible lead time but decades of accepted data. AM may have excellent responsiveness but require new material/process evidence, inspection substantiation, machine equivalence work and component-level testing.

    A simple decision rule is:

    Choose AM when the present value of avoided lead time, inventory, tooling, scrap and supply risk is greater than the qualification penalty plus the new recurring AM constraints.

    A five-case screen

    CaseLikely answerWhy
    Low-volume Ti bracket, heavy machining from billet, non-fracture-criticalAM candidateMaterial savings + no tooling + manageable evidence burden.
    High-volume rotating engine diskForging remains favoredExtreme property/defect-tolerance requirements and mature forged pedigree.
    Complex combustor or thermal-management featureAM can winGeometry creates functional value conventional processes struggle to achieve.
    Legacy casting with broken tooling and 18-month supplier lead timeAM worth screeningObsolescence and tooling avoidance can dominate if qualification scope is bounded.
    Simple commodity geometry with stable qualified forging supplyStay conventionalAM adds cost and qualification with little bottleneck value.

    The key procurement mistake

    Teams often compare the quoted AM part price with the quoted casting/forging price. That misses the point. The comparison should include calendar time, tooling cash, inventory, material yield, minimum order quantities, supplier concentration, engineering-change responsiveness, post-processing queues, inspection throughput and qualification cost.

    AM is not automatically cheaper. It can be economically superior because it changes the shape of the constraint.

    Sources & further reading

    This decision framework is directional. Flight-critical manufacturing-route changes require application-specific engineering, quality and regulatory review.
  • How Long Does Aerospace AM Qualification Take? Cost, Timeline & Evidence Map

    How Long Does Aerospace AM Qualification Take? Cost, Timeline & Evidence Map

    Aerospace additive manufacturing can make a part quickly. Qualifying the material-process-machine-part system is usually the slower problem. The useful planning question is not “How fast can we print it?” but “How long until we have enough controlled evidence to release it for the intended application?”

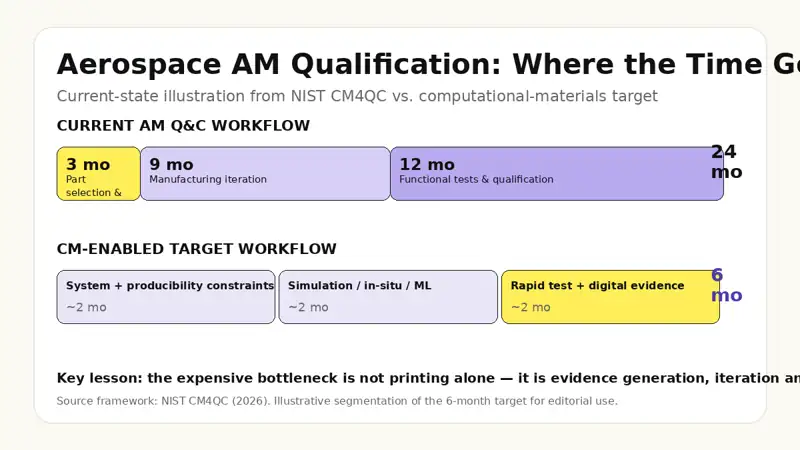
    Infographic comparing a 24-month current aerospace additive manufacturing qualification workflow with a 6-month computational-materials target workflow.
    NIST’s CM4QC program illustrates a current AM design-and-qualification workflow of roughly 24 months and a future computational-materials-enabled target of about 6 months. The future-state segmentation shown here is editorial/illustrative.

    The short answer: plan for an evidence program, not a print job

    For a low-criticality application using a mature alloy/process combination, qualification burden can be modest. For a new flight-critical component, a new alloy, a new machine family, or a design with hard-to-inspect internal features, the evidence program can dominate the schedule and the budget.

    The 2026 Computational Materials for Qualification and Certification (CM4QC) program is unusually useful because it frames the bottleneck directly. NIST’s project page shows a representative current AM workflow of about 24 months: roughly 3 months for part selection/design, 9 months for manufacturing iteration and 12 months for functional tests and qualification. Its future-state vision compresses that to roughly 6 months by using simulation, in-situ data, machine learning, NDT and digital evidence more effectively.

    The underlying NASA/FAA/NIST CM4QC strategy document, published in 2026, is explicit about the problem: traditional qualification and certification approaches can create high costs, long development timelines and repeated design/process iterations for process-intensive materials such as metal AM.

    A practical aerospace AM qualification timeline

    PhaseWhat happensTypical schedule risk
    1. Part & requirement definitionCriticality, loads, environment, life requirement, failure modes, acceptance criteria.Requirements change after manufacturing work has already started.
    2. Material/process definitionAlloy, powder/feedstock controls, machine, parameter set, build layout, heat treatment, HIP, machining.The process window is not stable or is too machine-specific.
    3. Build iterationCoupons, witness specimens, distortion control, support strategy, defect reduction, repeatability.Iterations multiply because design and process are coupled.
    4. Property & defect characterizationMicrostructure, tensile, fatigue, fracture, creep as applicable; defect population and sensitivity.Data scatter or defect mechanisms force another build campaign.
    5. Inspection & acceptanceNDT strategy, CT where needed, surface condition, dimensional inspection, acceptance limits.Inspection capability cannot resolve the defect size/location that matters.
    6. Component substantiationFunctional, proof, durability, environmental or other application-specific tests.Test failure exposes a design/process interaction not covered by coupons.
    7. Configuration & change controlFreeze the qualified envelope and define how changes are assessed.A “small” machine, parameter, supplier or post-process change triggers new evidence.

    Where the money actually goes

    Public sources rarely give a clean component-level qualification price because programs differ radically and most detailed cost data are proprietary. But the cost structure is predictable. NIST notes that empirical material qualification can require thousands of tests, cost millions of dollars and take years when a full statistical approach is required. For a specific aerospace AM component, the relevant question is how much of that evidence already exists and can legitimately be reused.

    • Build campaigns: machine time, feedstock, witness coupons, failed builds and design/process iterations.
    • Post-processing: heat treatment, HIP, machining, surface finishing and special processes.
    • Characterization: metallography, chemistry, density/porosity, residual stress and dimensional work.
    • Mechanical testing: the cost jumps when fatigue, fracture, creep or environment-specific testing is needed.
    • NDT/CT: complex internal geometries may make inspection one of the pacing items.
    • Engineering & documentation: statistical analysis, process control plans, material/process specifications, configuration management and the qualification package itself.
    • Rework and requalification: the most expensive dollar is often the one spent after the team discovers that a requirement, process variable or inspection limit was never frozen.

    The evidence map: what must connect to what?

    A useful qualification package is not a pile of test reports. It is a connected argument that links manufacturing inputs to material state, defect state, part performance and acceptance controls.

    Evidence layerQuestion it must answerExamples
    FeedstockIs the input material controlled and traceable?Chemistry, PSD, morphology, reuse limits, contamination controls.
    Machine & processCan the defined process repeatedly create the intended material state?Machine calibration, parameter envelope, monitoring, build records.
    Material stateWhat properties and variability result?Microstructure, tensile, fatigue/fracture/creep as relevant.
    Defect stateWhat defects exist, and how do they affect performance?Porosity, lack of fusion, inclusions, surface-connected defects.
    InspectionCan production inspection detect what the design assumes it can detect?CT/NDT capability, POD, dimensional inspection, surface inspection.
    ComponentDoes the real part behave as the models/coupons predict?Proof, functional, durability and environmental testing.
    Production controlHow will every future part stay inside the qualified envelope?Acceptance criteria, SPC, witness strategy, change control.

    Where programs most often get stuck

    1. The design moves faster than the qualification basis

    AM encourages rapid geometry iteration. Qualification rewards configuration stability. If teams keep optimizing after test articles are produced, the evidence package can become disconnected from the final released configuration.

    2. Machine equivalence is assumed instead of demonstrated

    “Same model of machine” does not automatically mean “same qualified output.” Laser condition, recoater behavior, gas flow, calibration, software state and maintenance history can matter. A scaling plan needs an explicit equivalence strategy.

    3. Inspection is treated as a downstream activity

    Internal channels and topology-optimized structures may be manufacturable but difficult to inspect. If the required defect tolerance is below the practical capability of the selected NDT method, the problem is architectural, not just procedural.

    4. The post-process becomes the real process

    Heat treatment, HIP, machining and surface finishing can control final properties as much as the build itself. Qualification plans that focus narrowly on the printer often discover the real release gate later.

    How to reduce qualification effort without lowering the bar

    1. Reuse evidence deliberately. Start from an alloy/process/machine/post-process combination with credible prior data when possible.
    2. Freeze the evidence architecture early. Define which claim is supported by simulation, coupon data, NDT, process monitoring and component testing.
    3. Design for inspectability. Treat NDT capability as a design input.
    4. Separate development variables from production variables. Experimental freedom is useful early; qualification needs a controlled envelope.
    5. Plan machine and supplier scaling before the first qualification build. Otherwise capacity expansion can trigger a second evidence campaign.
    6. Use computational methods where they reduce—not hide—uncertainty. That is the core direction of CM4QC: mature computational-materials methods so they can support qualification arguments and reduce unnecessary empirical burden.

    A planning rule

    The qualification burden rises when novelty, criticality, hidden geometry and configuration variability rise at the same time.

    That is why two parts made from the same alloy on the same AM process can have completely different qualification economics. One may be a straightforward substitution. The other may be a new material-process-design-inspection system that needs its own evidence architecture.

    Sources & further reading

    Editorial note: time and cost ranges in aerospace qualification depend on application, authority, criticality, prior evidence, process maturity and organization-specific certification basis. This article is a planning framework, not regulatory guidance.

  • Materialise vs Protolabs: Two Different Routes to Digital Manufacturing Returns

    Materialise vs Protolabs: Two Different Routes to Digital Manufacturing Returns

    Research cut-off: October 5, 2026. Materialise (MTLS) and Protolabs (PRLB) give investors two different routes into digital manufacturing. The useful comparison is where each earns money, how much depends on additive manufacturing, and what evidence would justify greater confidence in future cash generation.

    Fresh evidence before the next earnings cycle

    Update, 28 October 2026: Materialise reported Q3 2026 results on 28 October 2026: revenue of €67.7 million (up 2.1%, or 4.9% excluding divestitures), Medical revenue up 9.7% to €36.5 million, adjusted EBIT of €2.5 million and net cash of €82.5 million. It reaffirmed its 2026 guidance (Materialise release). Protolabs has not reported yet; its Q3 2026 results are scheduled for 29 October 2026 (Protolabs announcement). The comparison below has not been updated.

    Materialise has continued the share-buyback program announced in October 2025. In the week of September 21–25, 2026, it repurchased 31,306 shares at an average price of €6.99, within a program authorized for up to €30 million. This is relevant to per-share capital allocation, but it does not answer the operating question of which additive activities are generating the highest returns. Materialise is scheduled to report Q3 2026 results on October 28.

    Protolabs has not yet reported a newer quarter than Q2, but on September 23 it highlighted robotics as a growing use case for its combined factory-and-network model. That supports the demand side of the digital-manufacturing thesis. The next financial test is whether broader application growth improves revenue, margin and cash while 3D-printing revenue itself stabilizes or returns to growth.

    CompanyLatest fresh signalNext hard evidence
    MaterialiseOngoing share buybackQ3 results on Oct. 28: segment growth, manufacturing profitability and cash conversion
    ProtolabsRobotics demand highlighted on Sept. 23Next quarterly report: total growth versus 3D-printing mix and margin

    Sources: Materialise buyback update; Materialise financial calendar; Protolabs robotics update.

    Two businesses, two investment questions

    Materialise combines industrial software, manufacturing services and healthcare applications. Its medical offering includes planning and design software alongside personalized solutions. Calling the entire company a printing service misses this mix; calling it entirely a software company does too. Company overview; healthcare portfolio.

    Protolabs supplies parts using CNC machining, injection molding, 3D printing and sheet metal. Its manufacturing offering combines internal facilities with a supplier network. Customers can therefore use different processes as a product moves from development toward production. Protolabs business overview.

    Addithive interpretation: Materialise invites a thesis about specialized workflows and application expertise. Protolabs invites a thesis about faster purchasing, production execution and customer relationships across processes. Neither thesis requires believing that every manufactured part will eventually be printed.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • Velo3D vs AML3D: Can Metal AM Growth Become Cash Returns?

    Velo3D vs AML3D: Can Metal AM Growth Become Cash Returns?

    Research cut-off: October 5, 2026. Velo3D: Nasdaq VELO, USD. AML3D: ASX AL3, AUD.

    Velo3D and AML3D are research candidates for investors seeking direct exposure to metal additive manufacturing. The central question is whether commercial growth can become sustainable cash generation per share. Their technologies address different applications, so this is a comparison of business economics and execution risk, not a claim that their machines are interchangeable.

    September developments: useful signals, not cash proof

    Velo3D joined the U.S. Government-Industry Data Exchange Program (GIDEP) on September 17, adding a quality and supply-chain resource relevant to defense programs. On September 23 it also announced technology and operations leadership changes aimed at advancing production at scale. These developments are strategically positive, but they do not replace the cash test: the company still needs accepted deliveries, sustained margin improvement and lower operating cash consumption.

    AML3D announced on September 22 that it is participating in an approximately A$3.9 million, three-year advanced-aerospace manufacturing project with industry and research partners including an aerospace prime. AML3D expects to contribute about A$0.53 million over the project, including A$130,000 of cash. The project can advance qualification of wire-arc tooling capability, but it should be treated as capability-building rather than contracted production revenue.

    CompanyNew evidenceWhat the next report must show
    Velo3DGIDEP membership and operations leadership changesLower cash burn, accepted deliveries and durable margin gains
    AML3DAerospace R&D project and qualification pathwayConversion from capability milestones into repeat paid orders

    Sources: Velo3D investor relations; AML3D aerospace project announcement.

    Two routes to manufacturing revenue

    Velo3D combines Sapphire printers, Flow software and Assure quality control in an integrated metal-printing offering. Company technology description. AML3D uses wire-arc manufacturing and describes three revenue streams: systems, component manufacturing, and recurring licenses, maintenance and support. AML3D FY2026 presentation.

    The investor should ask how each installed machine changes future economics. A profitable installation followed by repeat service and production revenue can create a durable relationship. An installation that requires extensive unpaid support can instead consume cash. The installed-base count is therefore an incomplete measure of business quality.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • Company Signal: 6K Additive and ADDMAN Lock 30-Month Ni718 Powder Supply

    Company Signal · 6K Additive / ADDMAN · October 10, 2026

    What changed

    ADDMAN entered a 30-month supply agreement with 6K Additive for Nickel Alloy 718 powder. The contract has a minimum value of US$8.1 million and can reach US$10.8 million. It includes dedicated stocking support and a structured revert buy-back program under which 6K will process returned powder through its UniMelt technology.

    This follows 6K Additive’s finalization of the US$27.4 million EXIM facility that funds expansion of its Burgettstown capacity for nickel, titanium and refractory powders.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • AM Bottleneck Brief #5: Critical Powder Capacity and Characterization Are the Scaling Gate

    AM Bottleneck Brief #5 · October 10, 2026

    Critical Powder Capacity and Characterization Are the Scaling Gate

    Qualified feedstock quality is necessary but not sufficient. Industrial AM scales only when high-specification powder can be produced, characterized and supplied at production rates with stable genealogy and economics.

    What changed

    On 2 October 2026, 6K Additive executed the final agreement for a US$27.4 million EXIM facility under the Make More in America Initiative, coordinated with Defense Production Act Title III. The financing supports expansion of nickel, titanium and refractory powder capacity at its Burgettstown, Pennsylvania site, including four new buildings and additional UniMelt equipment. Funds are available for drawdown through June 2028.

    Separately, ADDMAN announced a 30-month supply agreement with 6K Additive for Nickel Alloy 718 powder, valued at a minimum of US$8.1 million and up to US$10.8 million, including dedicated stocking and a revert buy-back program. This is a concrete commercial offtake for domestically produced critical alloy powder destined for aerospace, defense and energy programs.

    In parallel, ZEISS (via TCT Magazine interview, 5 October 2026) emphasized that powder characterization—particle size distribution, morphology, chemistry, contamination and flow—is a core process variable, not a certificate checkbox. SAE International issued AIR7359 in April 2026 as additional guidance for metal powder feedstock procurement and production, clarifying which characteristics are controlled in AMS-AM specifications and why others are not.

    The bottleneck

    The constraint is no longer the existence of printable powder. It is the combination of:

    • Production-scale throughput of critical alloys (Ti, Ni superalloys, refractories) that meets tight interstitial and morphology windows.
    • Consistent characterization data that machine OEMs, service bureaus and regulated end-users can use for process lock and equivalency.
    • Lot genealogy and reuse rules that survive volume production and multi-source qualification.
    • Capital and utilization that allow unit cost to fall without widening property variation.

    Without these, even continuous low-oxygen processes or new atomization lines remain pilot-relevant rather than release-relevant.

    Why this matters more than machine speed or single-lot certificates

    A certificate of analysis is a snapshot. Series production requires evidence that powder attributes remain inside the process window across lots, handling, and reuse cycles, and that characterization methods themselves are repeatable enough for multi-machine or multi-site qualification. Financing and offtake agreements matter because they fund the capacity that makes such evidence commercially available rather than laboratory-scale.

    Evidence to monitor

    • Utilization rates and yield at new or expanded powder lines (6K Burgettstown, IperionX Virginia, Amaero, others).
    • Customer qualification of production lots from the expanded capacity, not just development samples.
    • Consistency of characterization data (PSD, oxygen, morphology, flow) across multiple production campaigns.
    • Whether long-term supply agreements convert into recurring volume and multi-year renewals.
    • Adoption of standardized guidance such as AIR7359 into procurement and quality systems.
    • Unit cost trends versus property scatter as throughput rises.

    Companies exposed to the constraint

    IperionX (continuous HAMR/GenX pathway and 200 tpa target), 6K Additive (UniMelt expansion and offtake), Amaero (EIGA capacity), Carpenter Technology, ATI and other specialty materials producers. Inspection and metrology firms such as ZEISS are exposed through the characterization and acceptance side of the same gate.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • Who Actually Makes Money in Additive Manufacturing?

    Who Actually Makes Money in Additive Manufacturing?

    Investor guide | Research cut-off: October 5, 2026.

    Additive manufacturing can create value for customers without creating attractive returns for every supplier or shareholder. The useful investment question is who captures repeat, defensible profit as production expands—and how much of that outcome is already required by the stock price. Addithive’s framework starts with the flow of money from a paid application to cash generated per share.

    What changed since September 7

    Several fresh developments reinforce the framework in this guide without changing its core conclusion. Amaero postponed its proposed U.S. IPO, 6K Additive finalized a US$27.4 million EXIM facility for capacity expansion, Velo3D joined GIDEP for defense supply-chain participation, AML3D entered a three-year aerospace manufacturing R&D project, Materialise continued its share-buyback program, and Protolabs highlighted robotics as a growing digital-manufacturing application.

    The common lesson is that strategic relevance, capital access and qualification progress are not the same thing as durable earnings. Financing can extend runway; defense-network access can improve opportunity; R&D can expand capability; buybacks can improve per-share economics; and end-market demand can grow. Investors still need the bridge from those signals to recurring margin, cash conversion and sensible capital intensity.

    Fresh signalWhat it provesWhat it does not prove
    Government-backed expansion financeCapital is available for capacityThat new capacity will be fully utilized or profitable
    Defense network / qualification accessMore routes into programsAccepted production revenue or margin
    R&D participationTechnical capability is advancingCommercial order economics
    Share repurchasesCapital is being returned to shareholdersThat AM itself is the earnings driver
    Strong end-market demandCustomer need existsThat printing captures the largest profit pool

    Recent sources: Amaero; 6K Additive; Velo3D; AML3D; Materialise; Protolabs.

    Start with the customer’s economic reason to buy

    A manufacturing buyer needs a reason to accept the cost and complexity of a new production route. That reason might be a component that improves performance, a shorter replacement lead time, reduced inventory or a viable route for a difficult geometry. Investors should identify the customer benefit first, then ask which supplier can retain part of it through pricing and repeat business. Large theoretical markets do not answer either question.

    Map the profit pool before choosing the ticker

    Business modelPotential route to profitEvidence to demandCommon investment trap
    Qualified materialsRepeat feedstock purchases and differentiated processingCustomer retention, contribution margin and AM-specific salesTreating all aerospace alloy revenue as additive revenue
    Production systemsEquipment margin plus an installed-base service streamAccepted installations, service economics and operating cash flowConfusing shipments with profitable customer adoption
    Software and medical workflowsRepeated use of validated digital workflowsSegment profitability, retention and reinvestment requirementsApplying software multiples to the entire mixed business
    Manufacturing servicesRepeat orders and better use of productive assetsProcess-level revenue, utilization and cash return on capitalCalling all digital manufacturing growth 3D-printing growth
    Post-processing and inspectionRevenue attached to accepted production outputAM attribution, repeat contracts and capacity economicsAssuming technical necessity automatically creates pricing power

    This table is an analytical framework, not a ranking of current stock attractiveness. A necessary process can still be competitively supplied; a scarce capability can remain financially immaterial inside a large company.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • 6K Additive Signs Final US$27.4M EXIM Loan to Fund Pennsylvania Powder Expansion

    6K Additive Signs Final US$27.4M EXIM Loan to Fund Pennsylvania Powder Expansion

    October 2, 2026: 6K Additive Inc. (ASX: 6KA) said it has executed the final loan agreement for a secured financing facility of up to US$27.4 million from the Export-Import Bank of the United States (EXIM). The money supports the expansion of its metal-powder plant in Burgettstown, Pennsylvania.

    Financial context — updated October 5, 2026

    The loan matters more when viewed against 6K Additive’s current scale. For the half year ended June 30, 2026, operating revenue was approximately US$13.27 million, up about 73% from US$7.67 million in the prior-year period, while the net loss narrowed to roughly US$6.82 million from US$11.60 million. The company reported US$22.1 million of cash at June 30.

    The expansion target is also now easier to frame: 6K has described a plan to increase Burgettstown powder capacity from roughly 200 metric tons per year to about 1,000 metric tons per year. The EXIM facility sits alongside a US$23.4 million Defense Production Act Title III grant and IPO capital. The key question is therefore no longer whether funding sources exist, but whether added capacity converts into qualified, repeat customer demand without excessive working-capital absorption.

    Execution snapshotLatest disclosed figure
    H1 2026 operating revenueUS$13.27m
    H1 2026 net lossUS$6.82m
    Cash at June 30, 2026US$22.1m
    Powder-capacity ambition~200 → ~1,000 metric tons/year
    EXIM facilityUp to US$27.4m
    DPA Title III grantUS$23.4m

    Sources: 6K Additive expansion plan; H1 2026 report; Q2 2026 activity report.

    What was signed

    • EXIM’s board approved the loan on December 4, 2025, pending final documentation. This release closes that gap.
    • The facility has a six-year term, drawdown is available through June 30, 2028, and the first 12 months are interest-only, followed by five years of amortizing principal.
    • Up to US$25.2 million covers eligible project costs, and up to US$2.2 million finances EXIM’s 8.9% exposure fee on disbursements.
    • The rate is a fixed Commercial Interest Reference Rate set five business days before the first disbursement. The company cites a currently published rate of 5.38% and an all-in annual borrowing cost of about 6.86% at current rates, plus a 0.5% per-year commitment fee on undrawn amounts.

    What it funds

    6K Additive says the proceeds are immediately available to reimburse ongoing equipment and infrastructure purchases for the previously announced Burgettstown expansion, which covers four new buildings and more equipment to raise nickel, titanium and refractory powder output. The company names titanium, tungsten, C-103, nickel alloys and other powders made with its UniMelt microwave-plasma process. The loan was approved under EXIM’s Make More in America Initiative in coordination with the Department of War’s Defense Production Act Title III effort.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • Carpenter Technology vs ATI: Where Additive Manufacturing Fits in the Investment Case

    Carpenter Technology vs ATI: Where Additive Manufacturing Fits in the Investment Case

    Research cut-off: October 5, 2026. Securities: Carpenter Technology (NYSE: CRS) and ATI (NYSE: ATI).

    Carpenter Technology and ATI offer exposure to demanding materials applications, including additive manufacturing. The investment question is how much of their earnings actually depends on AM. Our interpretation: value their established businesses first, then require separate evidence before assigning meaningful value to additive growth.

    Update since the original draft

    Update, 28 October 2026: Carpenter Technology reported Q1 FY2027 results on 22 October 2026: net sales of $798.2 million, operating income of $196.4 million (up 28% year over year) and diluted EPS of $3.25. It maintained its FY2027 operating income outlook of $850–880 million (Carpenter release). ATI is scheduled to report Q3 2026 results on 29 October 2026 (ATI announcement), and its Investor Day on 12 November is still ahead. The financial periods used below have not been updated.

    No newer quarterly results have replaced the financial periods used below, and neither company has disclosed a new standalone additive-manufacturing revenue or profit figure. The next evidence points are now dated: Carpenter Technology will report Q1 FY2027 results on October 22, while ATI will hold an Investor Day on November 12.

    ATI currently frames its 2027 company-wide targets at US$5.2–5.4 billion of sales, US$1.0–1.2 billion of EBITDA and a 19–21% EBITDA margin. These targets strengthen the broader aerospace-and-defense earnings case, but they still do not isolate additive manufacturing. The core research rule therefore remains unchanged: value the disclosed businesses first and treat AM as an incremental option until repeat economics are visible.

    Next catalystDateWhat to look for
    Carpenter Q1 FY2027Oct. 22, 2026Cash generation, margin durability and any new AM-specific disclosure.
    ATI Investor DayNov. 12, 2026Program economics, capital allocation and whether AM receives measurable financial targets.

    Sources: Carpenter Technology, Oct. 1; ATI Investor Relations.

    Where additive sits in the business

    Carpenter Additive sells standard and custom metal powders, powder-management equipment and associated services. This places it upstream of printed-part production. Its opportunity is repeat material consumption as customers move into sustained manufacturing. Source: Carpenter’s AM offering.

    However, Carpenter Additive belongs to Performance Engineered Products (PEP), alongside titanium and distribution operations. PEP is not an AM revenue proxy. In the June quarter, PEP generated $7.1 million of operating income, against $229.7 million in Specialty Alloys Operations, before corporate costs and eliminations. Standalone additive revenue and profit are not disclosed in this release. Source: Carpenter FY2026 results and segment definitions.

    ATI has a more direct finished-component proposition. Its Margate, Florida facility combines printing, heat treatment, machining and inspection. ATI announced commissioning in February 2025 and identified a Bechtel Plant Machinery contract supporting the U.S. Naval Nuclear Propulsion Program. That establishes a named customer application; the announcement does not establish the contract’s revenue, margin or consolidated earnings contribution. Source: ATI commissioning announcement.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • Amaero Has Built U.S. Powder Capacity—Can It Turn Scale Into Reliable Defense Supply?

    Amaero Has Built U.S. Powder Capacity—Can It Turn Scale Into Reliable Defense Supply?

    Amaero has completed the first major build-out of its U.S. refractory and titanium powder platform. Three EIGA atomizers are commissioned, FY2026 revenue reached a record level and titanium production has resumed after a six-week safety pause.

    The company now has strategically relevant capacity for defense, space and aerospace supply chains. But nameplate capacity is not the same as qualified output, customer utilization or durable cash generation.

    Update — October 5, 2026

    The biggest new development is financial-market execution, not manufacturing capacity. Amaero postponed its proposed U.S. IPO on September 23 because of adverse market conditions. The underlying registration statement remains on file, but the delay removes the near-term assumption that a U.S. listing will automatically provide fresh capital.

    A September 18 Form S-1/A also adds useful cash-flow context: for the six months ended June 30, 2026, Amaero reported a US$13.4 million net loss from continuing operations and US$12.9 million of net cash used in operating activities. The filing says near-term liquidity needs include operating losses during the commercialization ramp, working capital, the fourth EIGA atomizer, the argon-recycling system and debt service. That makes utilization and cash conversion as important as installed tonnage.

    Fresh evidenceInvestor implication
    U.S. IPO postponed on Sept. 23Capital-markets timing is now an explicit risk variable.
    H1 2026 operating cash use: US$12.9mRevenue growth has not yet made the platform self-funding.
    Atomizer #4 and argon system remain plannedFurther capacity should be judged against contracted demand and liquidity.

    Primary sources: Amaero IPO postponement; Amaero Form S-1/A filed September 18, 2026.

    Addithive verdict

    Thesis status: Capacity and commercial traction are strengthening; operational reliability is now the key risk.

    Amaero has created a scarce domestic powder and PM-HIP platform. The next proof points are safe utilization, customer qualification, recurring orders, gross-margin progression and disciplined capital deployment.

    What changed?

    • Amaero commissioned its third EIGA Premium atomizer ahead of schedule.
    • The company now operates one refractory-alloy and two titanium-alloy atomizers.
    • Stated annual capacity is approximately 200 metric tons of refractory powder and 480 metric tons of titanium powder.
    • FY2026 revenue reached A$18.1 million, compared with A$3.8 million in FY2025.
    • Q4 revenue was a record A$7.8 million.
    • Thirty PM-HIP components were shipped during the quarter.
    • Titanium powder production resumed in July after a six-week safety pause.
    • No purchase orders were cancelled during the pause.
    • Approximately A$1.3 million of titanium powder revenue shifted into Q1 FY2027.
    • The U.S. redomiciliation is complete. Amaero postponed its proposed U.S. initial public offering on September 23, 2026, citing adverse market conditions.

    Why the third atomizer matters

    Refractory and titanium powders are increasingly strategic inputs for additive manufacturing, missile and space components, high-temperature systems and medical applications. Domestic capacity is limited, especially for spherical powders with consistent chemistry, morphology and particle-size distribution.

    Commissioning the third atomizer gives Amaero parallel titanium capacity and a dedicated refractory line. That can improve scheduling flexibility, reduce single-machine dependency and support multiple customer qualification programs.

    The real value, however, will come from qualified output—not theoretical tonnage. Customers must approve material, repeat orders and integrate the powder into production workflows.

    Revenue growth is now visible

    Amaero’s FY2026 revenue increased to A$18.1 million, broadly in line with guidance. The fourth quarter included powder shipments and 30 PM-HIP components, showing that the business is progressing beyond commissioning activity.

    The revenue base is still small relative to installed capacity and planned expansion. But the growth rate provides evidence that contracted demand is beginning to convert into recognized sales.

    Investors should continue to separate milestone-driven revenue from recurring demand. A durable thesis requires repeat powder purchases and ongoing PM-HIP production rather than isolated program deliveries.

    The safety incidents cannot be treated as a footnote

    Two contained fire incidents occurred at the Tennessee facility in May. The first injured two employees; the second occurred during remediation work and caused no injuries.

    Amaero paused titanium powder production for approximately six weeks and engaged Jensen Hughes to lead a comprehensive process, systems and facility review. Improvements included changes to equipment layout, remote activation, additional sensors, redesigned dust filtration and exhaust systems, and stronger grounding, bonding and PPE practices.

    The decision to pause production reduced near-term revenue but was necessary. Metal-powder operations involve combustible dust and require rigorous engineering controls. Safe, repeatable production is part of the manufacturing moat—not a separate compliance issue.

    The absence of cancellations is encouraging

    No customer purchase orders were cancelled during the shutdown, and approximately A$1.3 million of titanium powder orders were deferred rather than lost.

    That suggests customers were willing to tolerate the timing disruption and still require the material. It does not eliminate execution risk, but it supports the view that demand is tied to real supply needs rather than speculative interest.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.