Category: Bottleneck Briefs

Addithive research on industrial AM bottlenecks, release gates, qualification constraints and accepted-part economics.

  • AM Bottleneck Brief #9: The Hardmetal Binder-Jet Qualification Gate

    Evidence date: 28 October 2026 · Reviewed: 2 November 2026 · Process focus: tungsten-carbide binder jetting · Thesis: the release gate is qualified performance after sintering and finishing, not printhead capacity.

    An installed binder-jet printer is a start, not a qualified manufacturing route. Industrial hardmetals must survive a much longer sequence: fit-for-process powder, binder deposition, de-powdering and sintering, dimensional recovery, finishing, measurement and customer-specific acceptance. The bottleneck is repeatable accepted components, not green-part throughput.

    What materially changed this week

    Hyperion + HP (28 October 2026): Hyperion Materials & Technologies reported installing an HP Metal Jet S100 in its Barcelona production facility during October 2026, backed by a strategic preferred partner agreement. Hyperion introduced its CarbiForm tungsten-carbide ready-to-print powders, stating these were tested on HP’s Metal Jet system when paired with Hyperion’s sintering operations. This is physical equipment plus named feedstock–process testing, a materially more concrete milestone than a software render or future product promise.

    But the evidence stops here: the announcement does not provide independent customer qualification, qualification standards, actual serial acceptance rates, powder-to-part yield, production cost, or delivered volume. Commercialization intent is not established serial performance.

    Where the production risk moves

    • Powder and binder system: lot-to-lot chemistry, powder behavior and binder consistency determine whether the green part is reproducible.
    • Sintering and dimensional control: distortion, shrinkage and variation must stay within an acceptable process window over successive lots.
    • Properties and acceptance: finished density, hardness, strength, toughness, defect distribution and customer-specific specifications must be demonstrated for the intended component.
    • Finishing and inspection: expensive machining and verification can erase nominal print-speed gains; cost must be measured per accepted finished part.

    Independent, cross-process evidence of the downstream gate

    Precision Resource + 3D Systems (28 October 2026): the partners announced groundbreaking at two metal AM locations in Huntington Beach, California and Shelton, Connecticut. Alongside planned expanded production capacity, Precision Resource is adding in-house heat treatment and complex machining. Operations are targeted for Q1 2027, not yet running. This is a separate laser powder-bed-fusion workflow, not evidence that HP’s WC binder-jet process has passed qualification; it reinforces a common manufacturing constraint: the complete print-to-finished-part chain.

    Financial caution, not a process comparison: Materialise’s 28 October quarterly report showed Manufacturing segment adjusted EBITDA of -€0.257 million in Q3 2026, improved from -€0.845 million one year earlier. Those figures are from a different company and mixed AM service activities; they do not establish why tungsten-carbide binder jetting succeeds or fails. They do illustrate why production activity and profitable output are different metrics.

    What evidence would change the thesis?

    • Qualification: named customer production part, governing requirements, test methods and accepted property distribution across repeat lots.
    • Repeatability: measured sintering shrinkage, dimensional capability, scrap/rework and a validated control plan.
    • Economics: yield-adjusted piece cost after sintering, finishing, inspection and any requalification, against conventional hardmetal routes.
    • Commercial adoption: repeat orders and delivered finished-component throughput, not installed printer count or hypothetical part designs.

    Company → Signal → Newsletter evidence loop

    HP Inc. company profile → HP/Hyperion tungsten-carbide Company Signal. 3D Systems company profile → Precision Resource expansion Company Signal. Materialise profile → AM Company Signals → AM Bottleneck Brief archive and subscription page. Email dispatch remains withheld pending independent delivery checks.

    Primary sources, source publication dates and review date

    Addithive review: 2 November 2026. Company announcements are primary statements, not independently audited production validations. The bottleneck and next-evidence framework are Addithive editorial interpretation; not investment advice.

  • AM Bottleneck Brief #8: Domestic Titanium Powder Ramp Is the Near-Term Gate

    Industrial additive manufacturing and powder metallurgy for defense and aerospace still depend on limited, often foreign-linked titanium metal and powder. The binding constraint is not installed printer count; it is consistent chemistry, morphology, oxygen control and qualified volume from domestic capacity that can be contracted and scaled.

    The bottleneck: qualified domestic titanium powder at meaningful volume

    On 29 October 2026 IperionX reported September-quarter production of 8.7 metric tons of titanium HAMR powder, up from 1.4 tons in the June quarter. A 1.6-ton back-to-back deoxygenation run in 63 hours validated furnace capacity above the 200 tpa target annualized rate. The company closed the quarter with 19 tons of finished powder and 207 tons of scrap feedstock. It also commissioned additional HSPT sintering capacity and validated a GenX continuous platform at an equivalent ~100 tpa rate with step-change unit economics (6x throughput, >75% lower power).

    These figures are primary-company production evidence, not capacity claims alone. They move the domestic scrap-to-powder route from pilot demonstration toward the volume needed for serial defense fasteners, components and AM feedstock. Qualification of alloy lots, customer sign-off and conversion of programs into recurring revenue remain the subsequent gates.

    Why it matters

    U.S. defense and aerospace titanium supply has long depended on limited primary capacity and foreign sponge. Scrap-based, low-oxygen powder routes that can be qualified for AM and powder metallurgy reduce that dependency, but only if volume, consistency and cost track the demand. The September numbers supply the first material quarterly production step against the near-term 200 tpa target. Downstream sintering relief and Army follow-on fastener orders show the chain extending beyond powder.

    Company exposure remains early: revenue is not yet material, cash burn continues, and dilution risk is present. The bottleneck ownership is real; financial materiality is still emerging. See the IperionX investor profile for the full scorecard and the Company Signals archive.

    Sources: IperionX September 2026 Quarterly Report, 29 October 2026.

    Research use only. Not investment advice.

  • AM Bottleneck Brief #7: Qualified Large-Format LPBF Capacity Is the Munitions Scaling Gate

    AM Bottleneck Brief #7 · 24 October 2026

    The binding constraint this week is qualified large-format laser powder bed fusion (L-PBF) capacity. On 22 October 2026, Nikon Advanced Manufacturing (Nikon AM) announced a Department of War contract for multiple L-PBF systems with a 2 m z-height, for Tomahawk mid-bodies. Nikon’s largest production system today, the NXG 600E, builds to 1,500 mm. Missile demand is under contract. Machines tall enough for these parts, qualified for flight hardware, are still being built.

    What changed

    • 22 Oct 2026, Nikon AM. Contract with the Department of War under the Industrial Base Analysis and Sustainment (IBAS) program, awarded through the Cornerstone Other Transaction Authority (COTA). Scope: multiple specially developed L-PBF systems with 2 m z-height, based on the NXG-E platform, for Tomahawk Land Attack Missile (TLAM) mid-bodies and similar applications. Work runs at the Nikon AM Technology Center in Long Beach, California, for prototypes and to scale production capacity. The release gives no contract value and no unit count. (Nikon AM)
    • 17 Aug 2026, RTX. Raytheon received a $22.9 billion, seven-year Tomahawk contract that supports the ramp to more than 1,000 missiles a year. RTX says it delivered three times more Tomahawks in the first half of 2026 than in the first half of 2025. (RTX)
    • 21 Oct 2026, 3D Systems. Opened a ~50,000 sq ft Industrial Technology Center in Littleton, Colorado, for application development, qualification and production of aerospace, defense and semiconductor-equipment parts. The site lists AS9100D, ITAR and CMMC Level 2. 3D Systems also names large-format printer manufacturing in South Carolina and a U.S. Air Force-sponsored system program in California. (3D Systems)
    • 6 Oct 2026, Velo3D. Mears Machine ordered its sixth Sapphire XC. Velo3D’s CEO: “The test of production additive manufacturing is whether a customer can qualify once and then continue adding capacity and materials as demand grows.” (Velo3D)

    The bottleneck

    Envelope first. Nikon calls the Tomahawk systems “specially developed.” In July 2026 Nikon described the NXG 600E (600 × 600 × 1,500 mm, twelve 1 kW lasers) as the largest machine Nikon SLM Solutions makes. A 2 m z-height is a taller machine class than that. In the same release, Beehive Industries called ultra-large-format printing capacity “currently limited in the domestic market.” (Nikon SLM Solutions, 7 Jul 2026)

    Qualification second. A new machine class must pass installation and equipment qualification before any part qualification counts. Methods are not yet common. ASTM’s F42 work item WK98852 states that “not all machine OEMs or machine users are using similar methods, or covering the same requirements even after 10+ years of PBF-LB/M.” It aims to refine installation/equipment qualification (IQ/EQ) and machine KPIs, building on ISO/ASTM 52945. (ASTM WK98852)

    The constraint is therefore not printer count. It is qualified machine-hours in an envelope large enough for munition structures, plus the ability to add a second and third machine without restarting qualification.

    Why it matters

    • Demand is contracted. RTX’s $22.9 billion award and its 1,000-a-year target set the rate. AM can only take part where a qualified large machine exists.
    • Large-format supply is concentrated. The named suppliers this cycle are Nikon AM (2 m NXG-E systems), 3D Systems (Air Force large-format program; Littleton qualification site) and Velo3D (Sapphire XC fleets at contract manufacturers).
    • Value goes to qualify-once, copy-many capacity. This is the machine-equivalence problem from our machine equivalence analysis, now at missile scale.
    • Gaps remain. Nikon gives no contract value, unit count or delivery date. No source here says AM mid-bodies are in the Tomahawk production configuration.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • AM Bottleneck Brief #6: Material Interchangeability Is the Qualification Gate for Defense AM

    AM Bottleneck Brief #6 · 17 October 2026

    In October 2026, America Makes and NCDMM named two winning teams in the US$12.4 million MIAMI project call. Qualified powder is necessary. It is not sufficient. An AM alloy enters defense and aerospace programs at scale only when shared, pedigreed data shows it meets or exceeds the critical properties of the legacy wrought or cast alloy it replaces.

    What changed

    MIAMI stands for Maturation Initiative for Additive Metals Interchangeability. It is funded through the Office of the Under Secretary of War for Acquisition & Sustainment, via the Industrial Base Policy office (OSW WIRE). (America Makes announcement; NCDMM announcement)

    Team 1: Northrop Grumman leads, with Georgia Institute of Technology and Contextualize, LLC. Team 2: Fastech, LLC leads, with Pacific Engineering, Auburn University / National Center for Additive Manufacturing Excellence, Texas A&M University, Prime Tech Data Management, AML3D and Westmoreland Mechanical Testing & Research. (America Makes)

    Teams will select candidate parts, define performance requirements and generate shared, validated data. The stated goal is cross-platform use of AM materials, less redundant testing and faster qualification across the defense industrial base. (America Makes)

    The bottleneck

    The constraint is material interchangeability under weapon-system requirements. Each program has typically built its own pedigreed data package. That duplicates testing. It keeps AM material substitution a one-off qualification exercise rather than a standard industrial path.

    A NASA technical memorandum (March 2026) names traditional qualification and certification approaches as one of the most significant barriers to wider AM use in aviation, citing high cost and long certification timelines. (NASA/TM-20260001729, CM4QC strategy)

    Why it matters

    Powder capacity (see Brief #5) improves feedstock availability. It does not create interchangeable materials. Without shared substitution data, each new alloy or process still faces platform-by-platform testing.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • Casting vs Forging vs Additive Manufacturing: When Does AM Actually Remove the Bottleneck?

    Casting vs Forging vs Additive Manufacturing: When Does AM Actually Remove the Bottleneck?

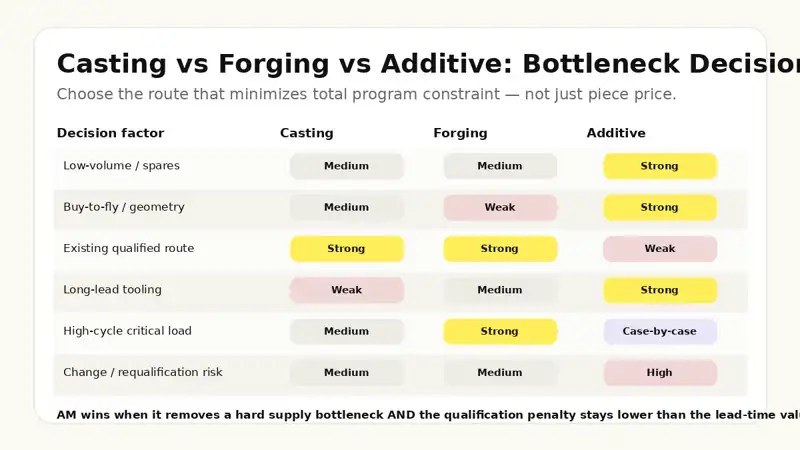
    Additive manufacturing does not remove every aerospace bottleneck. Sometimes it removes tooling and long-lead forgings; sometimes it simply moves the constraint into powder, HIP, machining, CT/NDT or qualification. The right comparison is total program constraint, not printer cycle time.

    Decision matrix comparing casting, forging and additive manufacturing across supply-chain and qualification factors.
    A practical decision map: AM is most valuable when it removes a hard supply bottleneck and the qualification penalty is smaller than the lead-time value created.

    Why this question matters in 2026

    Aerospace supply chains are still constrained by engines, electronics, castings, forgings, titanium and high-temperature alloys. Deloitte’s 2026 aerospace and defense outlook describes AM as a targeted resilience tool for low-volume, long-lead or hard-to-source parts—not as a universal replacement for conventional manufacturing.

    The constraint is visible in corporate actions, too. In September 2026, GE Aerospace announced an agreement to acquire Consolidated Precision Products, explicitly framing mission-critical casting capacity as necessary to support demand across commercial engines, aftermarket and defense. When an OEM is willing to spend billions to secure casting capacity, “just print it” is clearly not the default answer—but neither is “stay with the legacy route forever.”

    The bottleneck-removal test

    Before choosing AM, ask four questions in sequence:

    1. What is the actual constraint? Tooling? Raw material? Forge/foundry capacity? Buy-to-fly? Machining? Supplier minimum order quantity? Obsolescence?
    2. Can AM remove that constraint technically? Does the geometry, alloy, size and property requirement fit a mature process route?
    3. What new constraint does AM introduce? Powder/feedstock, build rate, support removal, HIP, heat treatment, machining, surface finish, CT/NDT, machine equivalence or qualification?
    4. Is the net program value positive? Compare avoided lead time and inventory against qualification, post-processing, yield and recurring cost.

    Casting vs forging vs additive: the decision matrix

    Part / program conditionCastingForgingAdditive
    High annual volume with stable geometryUsually strong once tooling/process are establishedStrong for load-critical shapes if capacity existsOften weak on unit economics unless geometry creates major value
    Low volume / spares / obsolescenceTooling and MOQ can hurtSmall lots can be difficultOften strong, especially with digital inventory
    Very high structural load / fatigue criticalityApplication-dependentOften preferred due to mature property pedigreePossible, but qualification and defect tolerance can dominate
    Complex internal flow pathsPossible but tooling/core complexity risesUsually poor fitStrong technical fit; inspectability may become the gate
    Extreme buy-to-fly ratioPotentially goodCan still require heavy machiningPotentially strong for expensive Ti/Ni alloys
    Long tooling lead timeWeak for urgent demandDies/tooling can constrain responseStrong if a qualified AM route already exists
    Existing mature qualified supply chainStrongStrongAM must overcome a qualification penalty to justify change
    Supplier capacity crisisMay be the bottleneckMay be the bottleneckCan be a resilience route if downstream AM capacity is actually available

    When AM genuinely removes the bottleneck

    1. Low-volume, long-lead hardware

    AM is strongest when tooling amortization is poor, demand is intermittent and carrying inventory is expensive. Legacy spares, defense sustainment hardware and space components often fit this pattern.

    2. Titanium or nickel parts with punitive buy-to-fly

    If the conventional route starts from a large billet or forging and machines most of it away, near-net AM can reduce raw-material exposure. That advantage is most valuable when alloy supply is constrained or scrap recovery does not fully compensate for long lead time.

    3. Tooling is the pacing item

    Investment-casting tooling, cores, forging dies and associated development loops can make the calendar inflexible. AM can collapse tooling time—but only if the AM process route is already mature enough to avoid replacing a tooling delay with a qualification delay.

    4. Part consolidation removes supplier interfaces

    A printed assembly that eliminates multiple details, welds, braze joints, fasteners or supplier handoffs may remove more schedule risk than its unit cost suggests. The value is system-level simplification.

    When AM only transfers the bottleneck

    • Powder/feedstock: a constrained or single-source alloy can recreate the same upstream dependency.
    • HIP and heat treatment: downstream special-process capacity may become the new queue.
    • Machining: AM rarely eliminates all machining for aerospace interfaces and critical surfaces.
    • CT/NDT: complex internal geometry can require expensive inspection with limited throughput.
    • Surface integrity: fatigue-critical parts may need substantial finishing and validation.
    • Qualification: the biggest trap is switching to AM to save six months of sourcing and then spending 18 months proving the new route.

    The qualification penalty

    The correct economic model should treat qualification like an up-front switching cost. A legacy casting or forging route may have terrible lead time but decades of accepted data. AM may have excellent responsiveness but require new material/process evidence, inspection substantiation, machine equivalence work and component-level testing.

    A simple decision rule is:

    Choose AM when the present value of avoided lead time, inventory, tooling, scrap and supply risk is greater than the qualification penalty plus the new recurring AM constraints.

    A five-case screen

    CaseLikely answerWhy
    Low-volume Ti bracket, heavy machining from billet, non-fracture-criticalAM candidateMaterial savings + no tooling + manageable evidence burden.
    High-volume rotating engine diskForging remains favoredExtreme property/defect-tolerance requirements and mature forged pedigree.
    Complex combustor or thermal-management featureAM can winGeometry creates functional value conventional processes struggle to achieve.
    Legacy casting with broken tooling and 18-month supplier lead timeAM worth screeningObsolescence and tooling avoidance can dominate if qualification scope is bounded.
    Simple commodity geometry with stable qualified forging supplyStay conventionalAM adds cost and qualification with little bottleneck value.

    The key procurement mistake

    Teams often compare the quoted AM part price with the quoted casting/forging price. That misses the point. The comparison should include calendar time, tooling cash, inventory, material yield, minimum order quantities, supplier concentration, engineering-change responsiveness, post-processing queues, inspection throughput and qualification cost.

    AM is not automatically cheaper. It can be economically superior because it changes the shape of the constraint.

    Sources & further reading

    This decision framework is directional. Flight-critical manufacturing-route changes require application-specific engineering, quality and regulatory review.

  • AM Bottleneck Brief #4: Qualified Feedstock Is Becoming the Release Gate

    AM Bottleneck Brief #4 · October 3, 2026

    Qualified Feedstock Is Becoming the Release Gate

    Industrial AM does not scale when powder is merely printable. It scales when material quality can be reproduced, traced and qualified at production throughput.

    What changed

    IperionX’s September 16 GenX validation is a useful signal because it connects material quality directly to scale. Across four continuous runs, the company processed more than 500 kg of titanium powder over 41 hours at roughly 12 kg/hour. Its spherical powder samples reported oxygen between 0.072% and 0.084%, below the 0.130% Grade 23 oxygen limit cited by the company. IperionX also reported six-times higher throughput versus its batch HAMR reference and more than 75% lower power consumption per kilogram.

    One day earlier, Kennametal introduced KAF82, a fully dense additive tungsten-carbide grade that it says has been commercialized at scale for metal-cutting applications. The company’s claimed lead-time shift—from months to weeks for certain custom hole-finishing tools—is important because the technical moat sits in powder metallurgy, densification and repeatable material performance, not geometry alone.

    The bottleneck

    Feedstock becomes a release gate when any of five things fail:

    • Chemistry: oxygen, nitrogen or other interstitials drift outside the qualified window.
    • Physical state: particle-size distribution, morphology, density or flowability changes build behavior.
    • Lot genealogy: virgin/reused blends and handling history cannot be reconstructed.
    • Downstream properties: the powder meets incoming limits but fails density, microstructure or mechanical-property requirements after processing.
    • Throughput: high-quality powder can be produced only in small development batches, making qualification commercially irrelevant.

    Why this matters more than printer speed

    A faster machine has limited value if every material lot needs exceptional handling, if oxygen pickup compresses the reuse window, or if the supplier cannot reproduce qualified powder at rate. The industrial metric is therefore not kilograms printed per hour. It is accepted kilograms released per unit of time with controlled material genealogy.

    Evidence to monitor

    • Powder chemistry distributions across multiple production lots—not one certificate.
    • Oxygen and nitrogen evolution through reuse cycles for reactive alloys.
    • Yield from incoming feedstock to accepted finished part.
    • Customer qualification of production-scale lots.
    • Capacity utilization at powder atomization, reduction, spheroidization and downstream finishing steps.
    • Whether unit cost declines as throughput rises without widening property variation.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • AM Bottleneck Brief #3: HIP / Thermal Processing Capacity as the Release Gate

    AM Bottleneck Brief #3 · As of 2026-09-19

    Extends: Brief #1 — Why Scale Fails After the Print. Adjacent: Brief #2 — CT / NDT Throughput as the Release Gate. Company names below are bottleneck-exposure mappings only, not investment advice.

    Short answer

    For many qualified metal AM routes, accepted-part release is limited by approved stress-relief, heat-treatment and HIP capacity—not by printer speed. When the locked route includes densification or a thermal property set, furnace/vessel slots, batch compatibility, recipe lock and qualification fill rate set ship rate. HIP is not universal, not a defect eraser, and not a substitute for inspection release.

    A finished build is not a released part. Release waits on the qualified thermal route—and on the queue to run it.

    Evidence labels used in this brief

    LabelMeaning
    FactSupported by current standard, primary authority or verified Addithive source
    Technical interpretationEngineering conclusion from multiple facts; conditions stated
    Addithive inferenceSynthesis for bottleneck / readiness analysis; not a published scientific fact
    Commercial signalCompany-reported capacity, filings, announcements—not technical proof

    Standing refusals

    • No investment advice; no buy/sell/hold language
    • No engineering certification or design allowables
    • No “HIP always”
    • No treating HIP as a universal defect fix
    • No equating capacity announcements with shorter customer queues
    • No treating demos or one-off HIP’d coupons as serial release proof

    1. The bottleneck

    Brief #1 framed the industrial metric correctly:

    Accepted output ≈ print capacity × availability × print yield × downstream yield × release rate.

    This brief isolates bottleneck #4 on the Addithive Atlas: Post-processing capacity and control—thermal sub-stack (stress relief, heat treatment, HIP when used). Brief #2 covered inspection/NDT (#5). Support removal and machining sit on the same Atlas row and are mapped on Addithive’s support-removal page; they are adjacent gates, not solved by HIP.

    After print the route still stops if:

    1. The locked baseline requires SR / HT / HIP and that step is not yet run under the qualified recipe.
    2. Approved capacity is scarce relative to build volume (slots, load size, alloy segregation, approvals, batch rules).
    3. Change or salvage logic is fuzzy—swapping furnaces, sites or cycles, or “HIP to fix the build,” without delta evidence.

    Fact: Industrial metal PBF routes commonly include post-processing before finished-part acceptance (ISO/ASTM 52908:2023; HIP necessary).

    Addithive inference: Where HIP or locked HT is on the critical path, queue time + batch fill + recipe lock + post-thermal verification become the release gate—even when printers and CT labs have spare capacity.

    Failure modeWhat breaksEvidence to track
    Recipe / baseline gapThermal step not lockedTraveler vs PPP; “standard HT” without load survey
    Capacity gapApproved vessel/furnace scarceQueue days; utilization; weekend backlog
    Batch-compatibility gapAlloy/size/cycle rules block fillPartial loads; contamination holds
    Distortion / property trade-offDimensions or strength outside casePost-thermal CMM scrap; strength debit
    Salvage overclaimHIP treated as cure for surface/FOD/chemistry/support damageMRB after “HIP salvage”; recurring defect codes
    Site switch without deltaNew furnace assumed equivalentOpen change approvals

    Standing refusal: HIP densification is not inspection release.

    2. The evidence

    Standards and qualification

    SourceWhat it anchorsBoundary
    ISO/ASTM 52908:2023Post-processing, inspection and testing for metal PBFFramework ≠ HIP mandate or part criteria
    ISO/ASTM 52920:2023Site QA across industrial AMSite QA ≠ flight/clinical approval
    NASA-STD-6030 / 6033Flight hardware + facility control (6033 revalidated Jan 2026)Agency-specific mental model
    Gate 4 (Checklist)SR/HT/HIP/machining/finish as applicableNo “HIP always”

    Fact: Gate 4 treats locked thermal post-processing as its own layer: furnace qualification, load control, cycle lock when HIP is used. Coupon HIP ≠ part-family HIP under uncontrolled loads.

    Technical evidence

    • When HIP is compelling: internal porosity HIP can address; fatigue/fracture cases sensitive to internal defects; or a governing specification requires it (HIP necessary).
    • What HIP does not fix: surface-connected defects, chemistry/contamination, missing stock, gross distortion, wrong channels, support damage, or unvalidated “heal by closure” claims (HIP limits).
    • Trade-offs are real: Aghayar et al. (2026) review HIP on AM metals (densification, microstructure, properties). Maj et al. (2025) on already-dense LPBF Hastelloy X: further porosity cut need not yield proportional mechanical gain; strength can fall as ductility/isotropy improve—so “HIP always” is too broad.

    Decision rule: state alloy, defect population (internal vs surface-connected), cycle (T/P/time/cool), subsequent HT, dimensional allowances and the property case—or do not claim HIP is required.

    Capacity and economics

    Fact: Accepted-part cost = total route cost / accepted released parts—including thermal cycles, distortion scrap and queues (Accepted-part cost).

    HookTrackRule
    Queue at approved HIP/HTLead time at qualified sitesIf queue binds, more printers raise WIP
    Batch fill / alloy segregationPartial loads; contamination holdsCapacity ≠ usable capacity
    Cycle + cool + handoffVessel occupancy vs calendar to releaseOccupancy ≠ ship date
    Post-thermal yieldDimensional/property scrap; salvage MRBsDensity alone ≠ throughput
    Switching / delta costNew site, vessel class, recipeApprovals make substitutability low

    Technical interpretation: Sequential stage yields compound; a thermal station that scrapes dimensions or forces re-machine destroys capacity.

    Addithive inference: Buying another printer when approved HIP/HT binds increases WIP, not shipments (Brief #1 / #2 pattern).

    Qualification touchpoints (Gate 4 — thermal)

    ItemWhy it stops releasePass signal
    SR / HT procedureStress, microstructure, distortionFurnace qual; load TCs; recipe locked
    HIP cycle (if used)Density, microstructure, dimensions, fatigueCycle + loads controlled; use/non-use explicit
    Add/remove HIPFull thermal-route evidenceSpec- or property-driven rationale
    Furnace / site switchEquivalency + traveler continuityDelta executed before serial move
    Load survey / rackingUniformity and contaminationSurvey current for load family
    Post-HIP HT / ageFinal properties are the routeSubsequent HT locked with HIP

    Industrial signals (commercial, labeled)

    SignalStatusWhy it maps here
    Bodycote eastern U.S.: vacuum HT, expanded HIP, Powdermet/AM support; Greenville HIP + HT + wire EDM for printed metal~21 Jul 2026 PR (Brief #1 lead)Hand-off reduction on printed → application-ready route
    Bodycote Europe: Magny-Cours large-format HIP; Haag-Winden +2 vesselsJul 2026HIP capital for A&D / IGT throughput
    Bodycote H1 2026 interim: Specialist Technologies ~16.7% organic; A&D growth inside ST28 Jul 2026Demand for thermal specialist network—not AM P&L proof
    Addithive Bodycote scores (profile as of 18 Jul 2026)Pure 2 / Bottleneck 5 / Serial / Emerging / Low subst.Editorial scarcity map—not a rating

    Commercial signal ≠ proof of shorter AM queues, immediate qualified fill, or AM financial materiality.

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • AM Bottleneck Brief #2: CT / NDT Throughput as the Release Gate

    AM Bottleneck Brief #2 · Research cutoff: September 12, 2026

    CT / NDT throughput as the release gate

    For many qualified metal AM routes, accepted-part release is limited by inspection/NDT capacity and locked acceptance criteria—not by printer speed.

    Extends Brief #1 — Why Scale Fails After the Print. Company names below are bottleneck-exposure mappings only, not investment advice.

    Short answer

    X-ray CT is often the binding method for complex internal geometry, but CT is not a universal filter: detectability depends on material, thickness, defect morphology, scan/reconstruction settings and validated POD. Monitoring does not replace CT/DT by default.

    A finished build is not a released part. Release waits on inspectability, disposition rules and queue time.

    1. The bottleneck

    Brief #1 framed the industrial metric correctly:

    Accepted output ≈ print capacity × availability × print yield × downstream yield × release rate.

    This brief isolates bottleneck #5 on the Addithive Atlas: Inspection, NDT and acceptance criteria. After print—and often after stress relief, HIP, machining and cleaning—the route still stops if there is no validated method, no accepted disposition criteria, or approved CT/NDT capacity is scarce relative to build volume.

    Failure modeWhat breaksEvidence to track
    Method gapCritical defects not coveredInspection plan vs FMEA; POD status
    Criteria gapFindings without accept/reject rulesOpen MRBs; disposition backlog
    Capacity gapQueue dominatesCT turnaround; scanner utilization
    False-call / over-rejectThroughput collapsesFalse-call rate; repeat scans
    Substitution overclaimMonitoring treated as CT replacementApproved substitution list

    Standing refusal: Voxel size is not the minimum detectable defect size. A successful demo scan is not serial inspection readiness.

    2. The evidence

    Standards and qualification

    SourceWhat it anchorsBoundary
    ISO/ASTM 52908:2023Post-processing, inspection and testing for metal PBFFramework ≠ part-specific criteria
    ISO/ASTM 52920:2023Site QA measures across industrial AMSite QA ≠ flight/clinical approval
    NASA-STD-6030 / 6033Flight hardware + facility control (6033 revalidated Jan 2026)Agency-specific mental model

    Technical evidence

    • CT is uniquely useful for 3D internal inspection of complex AM geometry; it is not universally superior to UT, PT, ET or radiography.
    • Recent literature supports the detectability boundary: Sun et al. (2024) review XCT across prevention, diagnosis and failure prediction in metal AM; Baig et al. (2025) show XCT performance deteriorates more for irregular lack-of-fusion defects than for near-spherical pores, with reliable capture often needing features several times larger than a voxel. Separately, a 2024 Ti-6Al-4V POD study found high detection rates can require flaw sizes substantially larger than nominal voxel size.

    Decision rule: describe detectability with material, thickness, morphology/orientation, scan/reconstruction settings and POD basis—or do not claim a detection limit.

    Monitoring does not erase the release gate

    NIST framing and Addithive’s substitution brief converge: telemetry ≠ sensing ≠ post-process NDT/CT ≠ destructive testing. A melt-pool image is not a pore measurement. Substitution needs measurand definition, registration, ground truth, POD, false-call behavior, robustness, locked analytics and approval—layered evidence, not automatic elimination of post-build inspection.

    Industrial signals (commercial, labeled)

    SignalStatusWhy it maps here
    Bodycote U.S. east-network HIP/HT/wire EDM for printed metal~21 Jul 2026Downstream capacity; inspection release remains separate
    Hexagon to acquire Waygate (~$1.45B; 2D X-ray / 3D CT, RVI, UT)Announced 13 Apr 2026; still pending as of 12 Sep 2026 — expected close H2 2026; no completion announcedCapital to NDT hardware + CT stack beside metrology/CT analysis
    America Makes JAQS-SQ; U.S.–UK AAMI2026NDT, acceptance criteria, portable evidence as scale constraints

    Update, 28 October 2026: Hexagon’s acquisition of Waygate Technologies is still pending; no completion has been announced. In its Q3 2026 interim report (23 October 2026), Hexagon said the deal “remains on track to complete in Q4 2026.” The table above has not been updated.

    Commercial signal ≠ proof that any vendor resolves AM CT throughput industry-wide.

    3. The exposed companies

    Mapping only—not investment advice. AM materiality is often emerging or immaterial at group level.

    RolePublic exposures (map)Analyze (not “buy”)
    CT / NDT systemsHexagon (VG; pending Waygate), Nikon, ZEISS; Waygate/Baker Hughes until closeCapacity, AM apps, software attach, integration risk
    Metrology / simulation adjacentHexagon, AMETEK (FARO/Creaform), Renishaw; Simufact / Ansys / Siemens / DassaultWhether dimensional or predicted risk sits on the release path
    Depends on CT to ship / densificationAerospace/defense adopters; ATI; Oerlikon; Bodycote (HIP)Internal-channel families; CT vs print queue; HIP ≠ inspection release

    4. The decision

    What changed

    • Inspection/NDT is the explicit release-rate limiter for complex accepted-part output.
    • Hexagon’s Waygate deal elevates NDT/CT strategically (close still pending as of 12 Sep 2026; H2 2026 target unchanged).
    • Defense work treats NDT + acceptance criteria + portable evidence as infrastructure.

    What remains unproven

    • Whether automated CT review materially raises accepted-part throughput without missed-defect risk in regulated apps.
    • Whether in-situ monitoring wins approved substitution on flight/clinical hardware at scale.
    • Whether NDT M&A shortens customer queue time or mainly consolidates share.

    What to watch

    1. CT turnaround/utilization at qualified labs (not demo times).
    2. POD / locked acceptance criteria for LPBF Ti and Ni.
    3. Count of approved monitoring substitutions.
    4. False-call and MRB rates after CT.
    5. Waygate close and any disclosed aerospace/AM CT backlog (H2 2026).
    6. Accepted-part yield vs build-success rate.

    Decision rule

    Before buying another printer, ask: critical defect population? Validated NDT/CT + POD? Locked acceptance criteria? Approved inspection capacity vs build volume? Approved monitoring substitution—or only complementary evidence? If the queue sits at CT/NDT disposition, more print capacity increases WIP, not shipments.

    Sources

    • Addithive: Brief #1; CT vs NDT; Monitoring substitution; Aerospace qualification; Bottleneck companies
    • ISO/ASTM 52908:2023 (current ed., iso.org stage 60.60); ISO/ASTM 52920:2023; NASA-STD-6030 / 6033
    • Sun et al. (2024), Thin-Walled Structures — XCT metal AM review; Baig et al. (2025), Scientific Reports 15:6740 — irregular LoF detectability; 2024 Ti-6Al-4V POD literature — high detection often requires flaws ≫ voxel
    • Hexagon / Baker Hughes Waygate announcement 13 Apr 2026; re-checked 12 Sep 2026 — close still pending (H2 2026)
    • Bodycote eastern U.S. AM post-processing (Jul 2026); America Makes JAQS-SQ / AAMI (2026)

    Continue the bottleneck research

    Download the free Industrial AM Bottleneck Atlas and receive one evidence-led bottleneck brief each week.

    Related: Research Hub · Tools · CT vs conventional NDT · Qualification Evidence Checklist · Brief #1.

    Addithive provides engineering-led research mapping. This article is not engineering certification, legal advice or investment advice.

  • From Prototype to Production: The Five Assets That Actually Create an AM Moat

    Additive manufacturing has no shortage of impressive hardware. What remains scarce is the ability to turn that hardware into repeatable, qualified production.

    That distinction matters because the strongest industrial moat in AM is rarely a printer by itself. It is a stack of assets that makes production easier to approve, repeat, expand and defend against competition.

    1. Qualified material data

    A process becomes more valuable when customers can design around trusted properties instead of commissioning a fresh characterization campaign. Material allowables, statistically robust datasets and accepted specifications reduce friction between a promising process and an engineering release.

    This is why milestones such as MMPDS inclusion or standardized material-property presentation matter more than they may appear. They make data reusable across decisions.

    2. A controlled process window

    Production AM needs more than a parameter file. It needs evidence that critical variables remain controlled and that machine capability can be verified over time. ISO/ASTM 52941:2026 formalizes machine qualification and requalification for aerospace LPBF, reflecting the broader shift from one-off build success toward managed manufacturing capability.

    3. Inspection and post-processing capacity

    The printed shape is not the finished product. Heat treatment, HIP where required, support removal, machining, surface finishing and nondestructive inspection can determine throughput and cost. Airbus’ serial A350 wire-DED implementation illustrates the point: deposition is followed by ultrasonic inspection and machining before installation.

    A supplier that controls these downstream steps can often scale faster than one that owns more printers but depends on constrained external processes.

    4. Qualification evidence that survives change

    The most valuable qualification system is not merely one that approves the first part. It is one that can handle the second machine, the next supplier, a maintenance event or a controlled process change without forcing the organization to rebuild its evidence base from zero.

    Programs such as JAQS-SQ and AAMI are important because they target supplier qualification, process-control documents and equivalence across production environments. CM4QC pushes the same problem from another direction by exploring how validated computational methods can make qualification evidence more reusable and targeted.

    5. Customer approval and recurring production

    The final moat is commercial, not technical. A process becomes difficult to displace when it is embedded in drawings, procurement systems, maintenance plans and qualified supplier networks. At that point the competitor is not trying to beat a print benchmark; it is trying to replace an accepted manufacturing route.

    Why these five assets compound

    Each asset makes the next one more valuable. Material data supports design approval. A controlled process produces repeatable properties. Inspection and finishing convert the build into accepted hardware. Reusable qualification logic makes capacity easier to expand. Recurring customer approval then improves utilization and generates more production evidence.

    That flywheel is much harder to replicate than a machine specification.

    Addithive view

    The AM companies most likely to create durable industrial value will own more than printing technology. They will own some combination of qualified material knowledge, process control, downstream capacity, reusable evidence and customer approvals.

    When evaluating whether an AM technology has crossed from prototype to production, ask a simple question: how much of this five-asset stack already exists?

    Sources

  • Why AM Machine Equivalence May Matter More Than Machine Speed

    Additive-manufacturing equipment makers compete on familiar metrics: laser count, build rate, chamber size and automation. But for regulated production, another metric may determine how fast capacity can actually scale: machine equivalence.

    The industrial problem is simple. A qualified AM process is usually tied to a defined machine state, material, parameter set and quality system. Adding another nominally identical machine does not automatically mean the new asset can enter production with zero qualification work.

    ISO/ASTM 52941:2026 makes the machine itself part of the formal evidence structure for aerospace laser powder-bed fusion. The standard specifies qualification and requalification requirements and can be used for periodic verification or after maintenance and repair.

    Why equivalence is a capacity issue

    If a factory needs six machines to support a production ramp, the business case depends on more than buying six units. The manufacturer must show that the machines operate within the validated production envelope and that meaningful differences are understood and controlled.

    The same challenge appears across sites and suppliers. America Makes’ Allied Additive Manufacturing Interoperability program is explicitly focused on AM equivalency and interoperability between U.S. and UK defense supply chains for critical LPBF parts. That is a strong signal that equivalence is becoming a system-level industrialization problem, not an academic detail.

    Speed that cannot transfer has limited value

    A new machine can be dramatically faster and still create qualification friction if its process physics, monitoring architecture or control logic differs enough from the existing qualified baseline. Conversely, a machine family that supports predictable transfer of process capability may create more usable production capacity even with less spectacular headline performance.

    What equivalence requires

    • Comparable machine-performance metrics
    • Defined calibration and maintenance controls
    • Evidence that critical process outputs remain inside the qualified envelope
    • Material and parameter traceability
    • A formal method for handling hardware, software and site changes
    • Statistical evidence linking machine state to part quality

    This does not mean every machine must be physically identical. The more useful goal is demonstrating that differences do not materially alter the characteristics that matter for the intended part and qualification basis.

    The strategic implication

    Machine vendors that make qualification transfer easier could gain an advantage that is difficult to see in a datasheet. Stable architectures, strong calibration systems, transparent process data and robust change-control practices may reduce the cost of adding the next machine — which is exactly when AM transitions from a technology project into a production network.

    Addithive view

    Industrial AM scale is not installed capacity; it is qualified interchangeable capacity. The market tends to reward faster printers, but aerospace and defense customers may ultimately reward platforms that make the tenth qualified machine easier to add than the first.

    That makes equivalence one of the least appreciated AM bottlenecks — and one of the most important.

    Sources